
Tax wrappers
Accounts held in an ISA, a pension, superannuation, an IRA or an RRSP are not taxed like an ordinary brokerage account. Set the account's tax wrapper and Borderfolio calculates its dividends, gains and US withholding at the wrapper's rates instead of the client's residence rates.
What a wrapper changes
A wrapper is set per account, so a client can hold a taxable account, an ISA and a pension side by side. For an account with a wrapper:
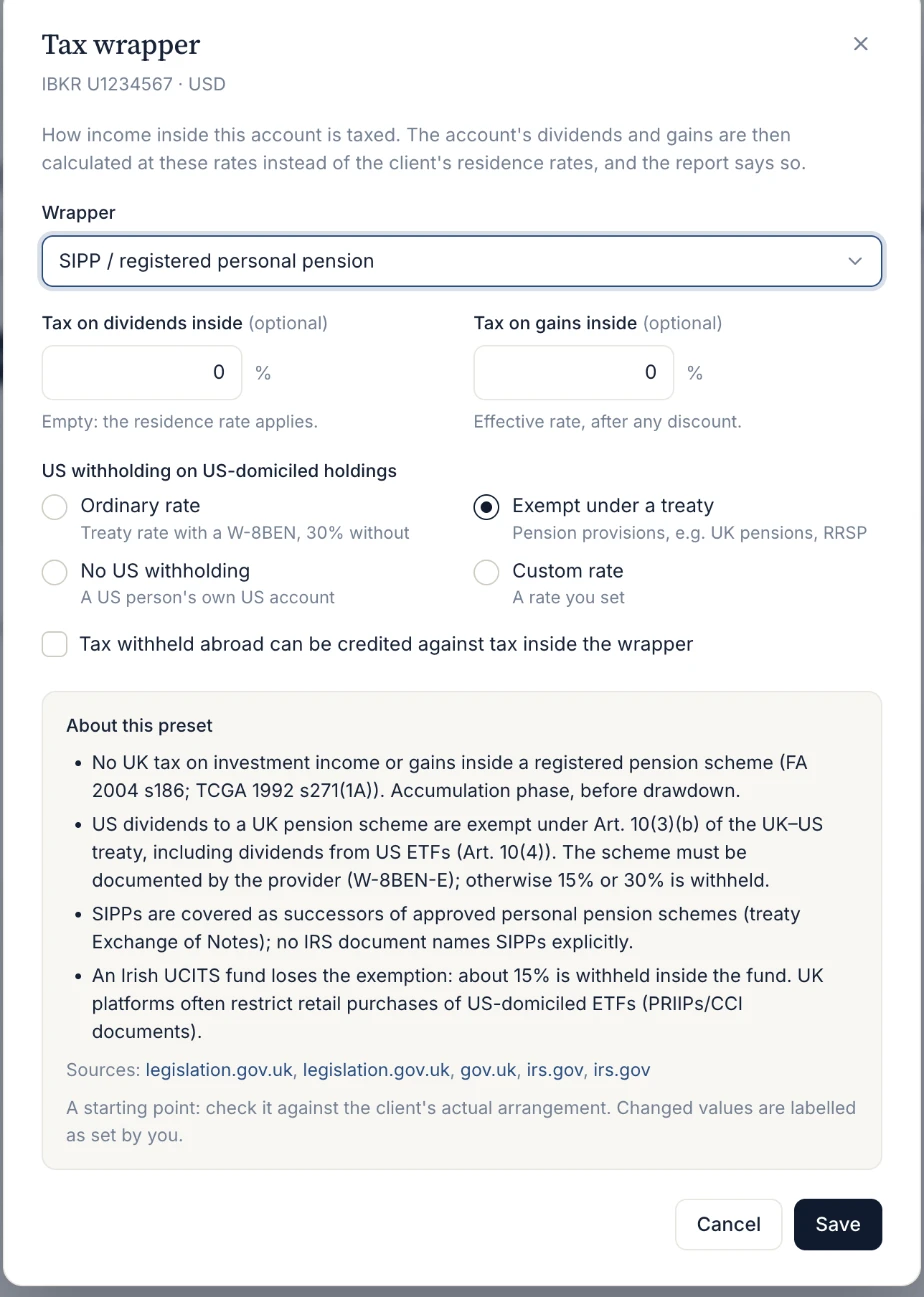
- Tax on dividends and on gains inside replace the residence's rates. A rate left empty keeps the residence's rate; it never reads as 0%.
- US withholding on US-domiciled holdings follows the wrapper: the ordinary treaty rate (with a W-8BEN, 30% without), an exemption under a treaty pension provision such as UK pension schemes or Canadian RRSPs, none for a US person's own account, or a rate you set.
- Credit for withholding: whether tax withheld abroad can be set against tax due inside the wrapper. Inside most wrappers there is no tax to credit against, so withholding is a final cost.
Every after-tax figure follows: the dividend withholding finding, dividends kept after all tax, the after-tax effect of an Irish fund in a scenario, and the tax on gains if sold. The scenario's tax basis card lists the accounts in wrappers and their rates, and the report states them.
Set a wrapper on an account
On the client's Portfolios tab, choose Tax wrapper on the account. Pick a built-in preset, one of your firm's own, or Custom to set the rates yourself. A preset fills the rates, with its notes and sources; you can change any value, and the account is then labelled as set by you rather than by the preset. Choose None to return the account to ordinary taxation.
Your firm's own wrappers
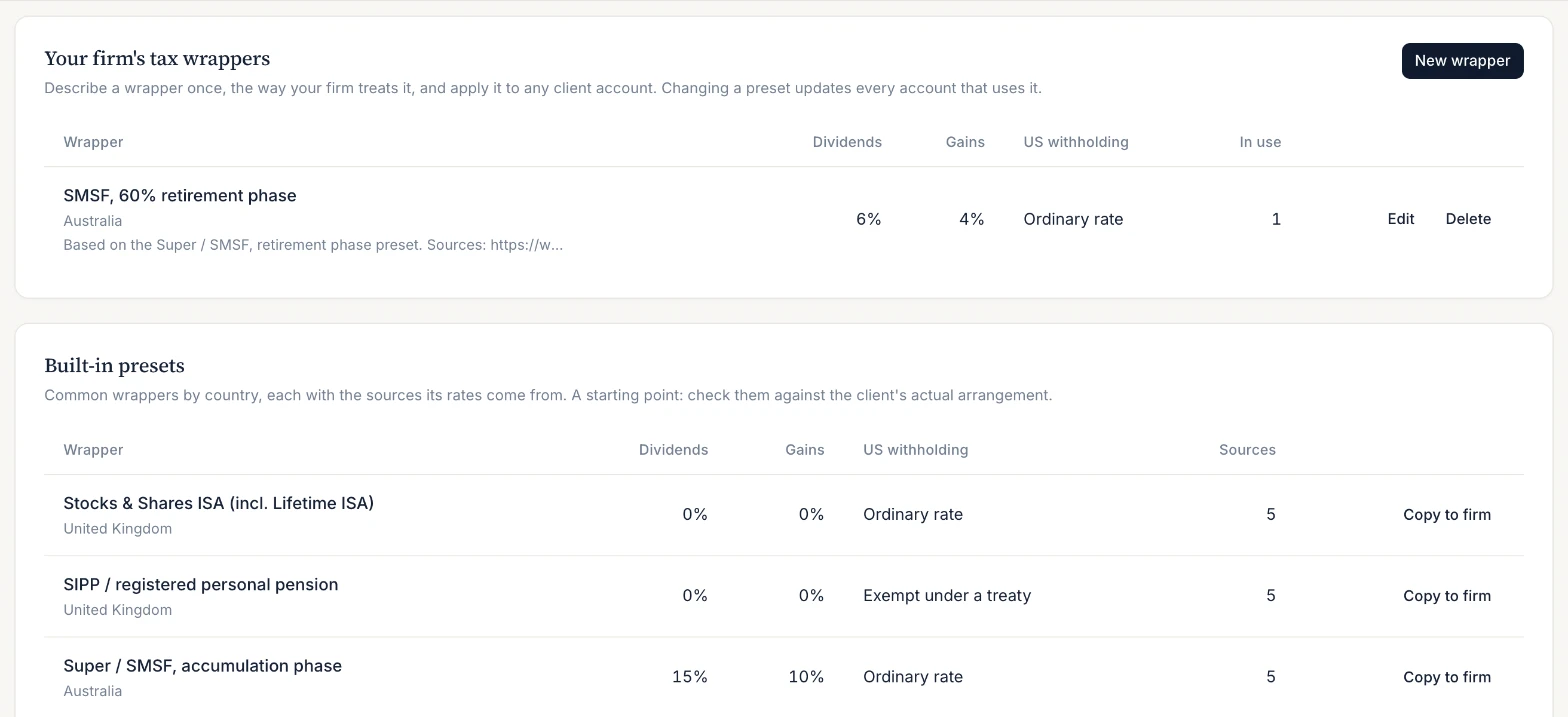
Under Settings, Tax wrappers, an owner can describe a wrapper the way the firm treats it, for example a self-managed super fund with a blended rate for its share in retirement phase, and every adviser can apply it. Start from a built-in preset with Copy to firm or from scratch. Changing a firm wrapper updates every account that uses it; deleting one leaves those accounts with the same rates as a custom wrapper, so nothing silently becomes taxable.
Built-in presets
The presets cover common wrappers in the United Kingdom, Australia, the United States, Canada, France and Ireland. Each value is taken from legislation, a tax authority or the relevant tax treaty, listed with the preset. They are a starting point: an individual arrangement, a transition period or a balance threshold can change the answer, so check them against the client's situation.
| Wrapper | Dividends inside | Gains inside | US withholding | Credit |
|---|---|---|---|---|
| Stocks & Shares ISA (incl. Lifetime ISA) United Kingdom | 0% | 0% | Ordinary treaty rate | No |
| SIPP / registered personal pension United Kingdom | 0% | 0% | Exempt under a treaty | No |
| Super / SMSF, accumulation phase Australia | 15% | 10% | Ordinary treaty rate | Yes |
| Super / SMSF, retirement phase Australia | 0% | 0% | Ordinary treaty rate | No |
| Traditional IRA United States | 0% | 0% | None (US person) | No |
| Roth IRA United States | 0% | 0% | None (US person) | No |
| 401(k) United States | 0% | 0% | None (US person) | No |
| RRSP / RRIF Canada | 0% | 0% | Exempt under a treaty | No |
| TFSA Canada | 0% | 0% | Ordinary treaty rate | No |
| PEA (plan d'épargne en actions) France | 0% | 0% | Ordinary treaty rate | No |
| Assurance-vie (unit-linked) France | 0% | 0% | Ordinary treaty rate | No |
| PRSA / personal pension Ireland | 0% | 0% | Ordinary treaty rate | No |
Stocks & Shares ISA (incl. Lifetime ISA) (United Kingdom)
- No UK tax on dividends, interest or gains inside the ISA (ISA Regulations 1998, reg. 22).
- The investor is the beneficial owner, so US dividends bear the ordinary 15% treaty rate with a W-8BEN (30% without); an ISA is not a pension scheme under the UK–US treaty.
- US withholding is a final cost: there is no UK tax inside the ISA to credit it against.
- Lifetime ISA: taxed the same way; a 25% charge applies to withdrawals other than at 60+, for a first home, on terminal illness or death.
Sources: legislation.gov.uk, legislation.gov.uk, gov.uk, irs.gov, gov.uk
SIPP / registered personal pension (United Kingdom)
- No UK tax on investment income or gains inside a registered pension scheme (FA 2004 s186; TCGA 1992 s271(1A)). Accumulation phase, before drawdown.
- US dividends to a UK pension scheme are exempt under Art. 10(3)(b) of the UK–US treaty, including dividends from US ETFs (Art. 10(4)). The scheme must be documented by the provider (W-8BEN-E); otherwise 15% or 30% is withheld.
- SIPPs are covered as successors of approved personal pension schemes (treaty Exchange of Notes); no IRS document names SIPPs explicitly.
- An Irish UCITS fund loses the exemption: about 15% is withheld inside the fund. UK platforms often restrict retail purchases of US-domiciled ETFs (PRIIPs/CCI documents).
Sources: legislation.gov.uk, legislation.gov.uk, gov.uk, irs.gov, irs.gov
Super / SMSF, accumulation phase (Australia)
- A complying super fund pays 15% on investment income. Gains on assets held 12 months or more get a one-third discount (10% effective); 15% if held for less.
- US dividends bear the ordinary 15% treaty rate: the Australia–US treaty has no pension exemption. The fund can offset it against its own 15% tax (foreign income tax offset, non-refundable).
- Franking credits on Australian dividends are not modelled here: they reduce the tax and can be refunded to the fund.
- Not modelled: Division 296 (extra tax on earnings above a $3m total super balance, from 1 July 2026), non-arm's length income (45%). A transition-to-retirement income stream is taxed as accumulation.
Sources: ato.gov.au, ato.gov.au, home.treasury.gov, irs.gov, ato.gov.au
Super / SMSF, retirement phase (Australia)
- Income and gains on assets supporting a retirement-phase income stream are exempt (exempt current pension income), within the transfer balance cap.
- US dividends still bear 15%, and it cannot be offset because the income is exempt: a final cost. A US-domiciled and an Irish fund then bear roughly the same 15%.
- A fund with both accumulation and pension interests uses the segregated or proportionate method; set a custom wrapper for a blended rate.
Sources: ato.gov.au, ato.gov.au, home.treasury.gov
Traditional IRA (United States)
- Earnings and gains are not taxed until distributed; distributions are ordinary income, with a 10% additional tax before 59½ unless an exception applies.
- Foreign tax withheld inside an IRA cannot be credited (IRS Info Letter 2010-0203). A non-US fund held in the IRA suffers US withholding inside the fund.
- Unrelated business taxable income (for example MLPs) can be taxed inside the IRA.
Sources: irs.gov, irs.gov, irs.gov
Roth IRA (United States)
- Qualified distributions (5-year rule, and 59½, disability, death or first home) are tax-free; earnings in other distributions can be taxed.
- Foreign tax withheld inside cannot be credited.
401(k) (United States)
- Deferrals and investment gains are not taxed until distributed; a designated Roth sub-account follows Roth rules.
- Investments are usually the plan's fund menu: foreign withholding is suffered inside the funds and cannot be credited.
Sources: irs.gov
RRSP / RRIF (Canada)
- Income is not taxed while it stays in the plan; withdrawals are taxable income.
- US dividends paid to an RRSP/RRIF are exempt under Art. XXI(2) of the Canada–US treaty, but only on US-listed holdings the plan owns directly. A Canadian-listed ETF holding US shares suffers 15% inside the fund.
- Foreign tax on income in an RRSP does not count for the foreign tax credit (CRA Folio S5-F2-C1, ¶1.69).
Sources: irs.gov, canada.ca, canada.ca
TFSA (Canada)
- Income and gains are tax-free, including on withdrawal.
- A TFSA is not a pension arrangement under the treaty, so US dividends bear 15% (derived from the treaty wording), and it cannot be recovered.
Sources: canada.ca, canada.ca, irs.gov
PEA (plan d'épargne en actions) (France)
- Income and gains reinvested in the PEA are exempt from income tax and social charges while they stay in the plan.
- Only EU/EEA company shares and eligible funds can be held: no direct US shares. Withholding by other EU countries is a final cost inside the plan.
- On withdrawal after 5 years the gain bears social charges (18.6% from 2026); before 5 years, income tax at the flat rate as well, with exceptions.
Sources: service-public.gouv.fr, service-public.gouv.fr, bofip.impots.gouv.fr
Assurance-vie (unit-linked) (France)
- No income tax while invested; switching between funds is not taxed. Gains are taxed on withdrawal (rates depend on the contract's age and premiums).
- The insurer owns the assets: US withholding is suffered inside the underlying funds.
- Social charges on the euro fund are levied each year as interest is credited; not modelled here. Check the current social-charge rate for assurance-vie before relying on it.
Sources: service-public.gouv.fr, service-public.gouv.fr
PRSA / personal pension (Ireland)
- Income and gains on PRSA assets are exempt (TCA 1997 s787I, s608); benefits are taxed on drawdown.
- The Ireland–US treaty has no 0% pension rate for dividends: 15% applies, usually inside the Irish funds held, and cannot be credited.
Sources: revenue.ie, irs.gov
What is not modelled
Tax on withdrawals from a wrapper (pension drawdown, early-withdrawal charges, social charges on a PEA withdrawal) is not included: the figures describe income and gains while invested. Division 296 and the split between accumulation and retirement phase in one fund are not calculated; use a firm wrapper with a blended rate where needed. Australian franking credits are applied inside a super wrapper once you enter them: see Australia and New Zealand. Withholding suffered inside a fund the wrapper holds, for example an Irish UCITS fund, is modelled at fund level as it is for any account.
Last updated . Describes the product as built; figures are screening estimates, not tax, legal or investment advice.