For advisers in the United Kingdom

From ISA and SIPPto reporting funds:one sourced review,under your name.

For a prospect before the transfer, a fixed-fee review of a DIY portfolio, or every client’s annual check: import the statements, check each offshore fund against HMRC’s reporting-fund list, see the excess reportable income to declare, a Section 104 cost that holds up and what leaving the UK would set in motion, then deliver a client-ready report in your firm’s name.

For advisers to US persons in the UK and to clients moving in or out, advice-only planners reviewing ISA, SIPP and general accounts at InvestEngine, Vanguard, Hargreaves Lansdown and AJ Bell, and boutique wealth firms.

The sample is a read-only UK demo firm: fictional clients, real prices. Ready for your own? Start a 30-day free trial, no card needed.

Illustrative: one client review — the statements, the cross-border brief, a finding and the report cover — drawn from the product's own components. Figures are examples, not client data. Reports are rendered from a stored snapshot and never change after later imports.

A real example

What one review found.

An accumulating fund pays nothing out and is still taxed. For this client, 1,850 units of Vanguard FTSE All-World (VWRP) in a general account mean about GBP 3,098 of income to declare for 2025-26 that never reached the account.

Why: VWRP is an Irish fund with UK reporting status, so each year it reports its income to UK investors; for the period to 30 June 2025, Vanguard reported USD 2.2479 a unit. Whoever held units at the period end is taxed on it as if paid on the fund distribution date six months later, 31 December 2025, which falls in 2025-26. The review takes the units from the confirmed transactions and the figure from Vanguard’s own report, and adds the same amount to the Section 104 cost, so it is not taxed again when the units are sold. The ISA and SIPP are left out: their income is not taxable.

Decision support for professional review, not tax advice. The tax itself is not computed: it depends on the client’s band and their other dividends. A fund held without an issuer’s report on file is named, never estimated.

In the workspace
Excess reportable income to declareESTIMATED · ATTENTION

For 2025-26 the client has about GBP 3,098 of excess reportable income to declare from funds held outside ISAs and pensions (as dividends). It is taxed although not paid out, and is deducted from the gain when the units are sold.

Assumes
1,850 VWRP units in the general account on 30 June 2025, the period end; received on 31 December 2025, the fund distribution date, at that day’s reference rate; ISA and SIPP left out
Source
Confirmed transactions; Vanguard Funds plc report to UK investors, period to 30 June 2025; HMRC HS265
In the client’s review
7Cross-border considerations
Excess reportable income to declare

The 1,850 units of Vanguard FTSE All-World (VWRP) held in the general account on 30 June 2025 carry excess reportable income of USD 2.2479 each, treated as received on 31 December 2025: about GBP 3,098 to declare as dividends for 2025-26. The same amount is added to the cost of the units in the Section 104 holding.

Units from the confirmed transactions, converted at the reference rate on the fund distribution date; HMRC’s helpsheet does not name the rate, so check the one used on the return. The ISA and SIPP are left out. The tax is not computed. Source: Vanguard Funds plc report to UK investors, period to 30 June 2025; HMRC HS265.
8Adviser notes

Your commentary, printed in its own section and never mixed with Borderfolio’s analysis.

Illustrative: the same finding as it appears in the workspace and in a generated review. Figures are examples, not client data.

Import. Find issues. Deliver. Keep reviewing.

Every step stays under your control. Nothing reaches a client’s holdings until you have reviewed and confirmed it.

  1. 01

    Import the statements.

    Upload the client’s statements from any broker, check what was extracted, and consolidate every account in their currency.

    Review importIBKR · 2026 Q3
    PositionSharesStatus
    VT · XNAS323New
    SMMCHA · XSWX7New
    VWRA · XLON410Unchanged
    Transactions found80 duplicates
  2. 02

    Find the issues.

    Costs, income, currency, fund domicile, withholding and residence matters, each with its source, its assumptions and what it does not cover.

    Consolidated view2 accounts · USD
    By trading currencyUSD 94.9% · CHF 5.1%
    Time-weighted return+16.6%annualised, since inception
    Money-weighted return+16.7%XIRR
    Expected annual income699.78 USDfrom trailing distributions
  3. 03

    Deliver the review.

    A client-ready PDF under your firm’s name, your commentary set apart from the analysis, frozen as generated.

    Portfolio reviewgenerated today
    Sections9summary to limitations
    Adviser commentaryIncludedlabelled as yours
    SnapshotFrozenreproducible on every download
    BrandingFirm namelogo and contact on Practice
04

Keep reviewing.

The accounts stay in the workspace. Import the next statements and the checks run again; last year’s report stays as sent.

  • The firm’s deskEvery client screened at once, most urgent first.
  • Reviews dueEach client’s review cycle, with offered, held and declined reviews recorded.
  • Reclaim deadlinesWithholding above the treaty rate, with the last day to claim it, across every client.
  • Before a moveThe same holdings at the new residence’s rates, and what leaving triggers.

The workspace

Built around the way advisers work.

Clients, imports, consolidated value, cross-border findings and reports, in one workspace your whole firm can use.

The firm’s desk

Who needs me this week?

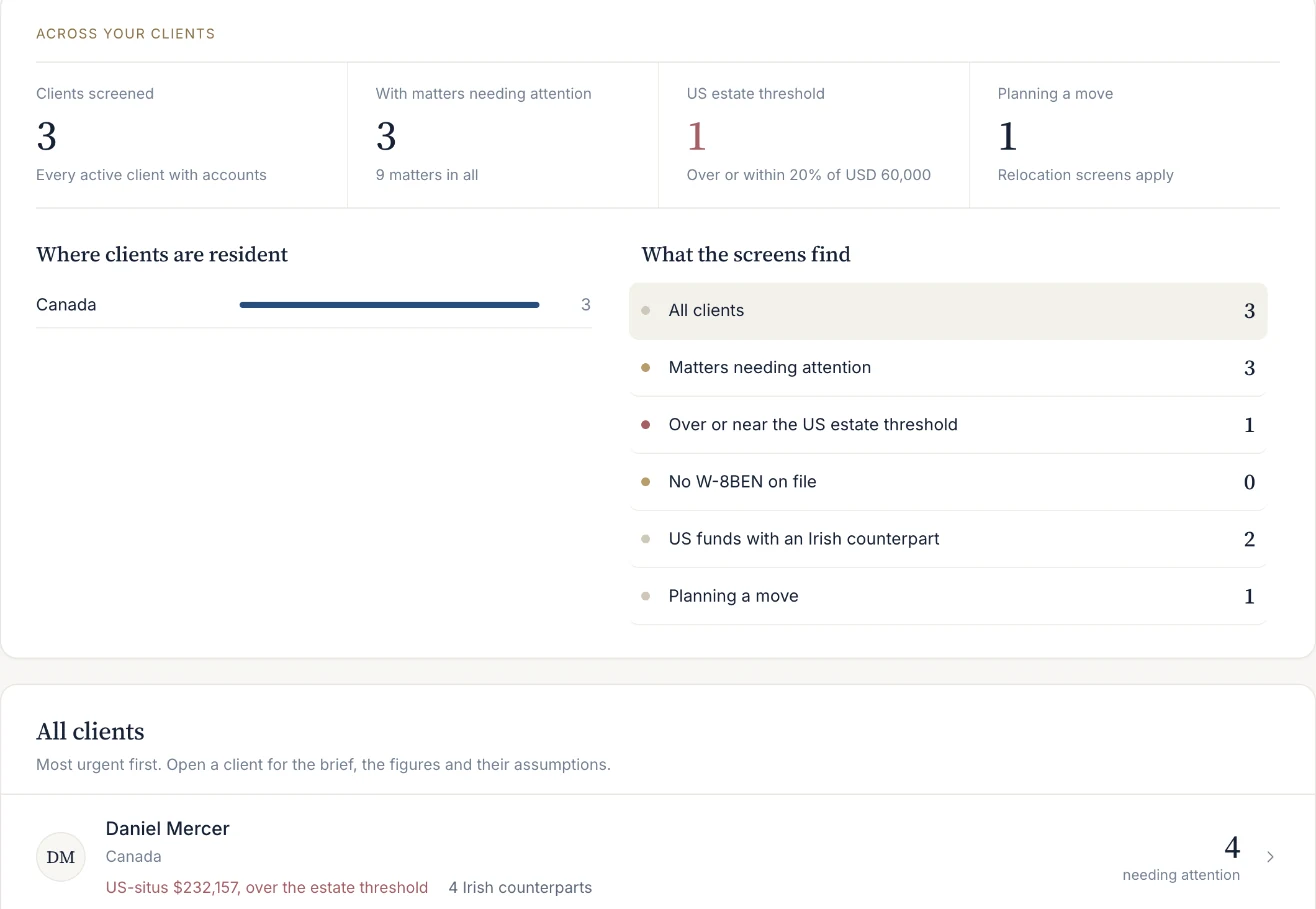
Every client screened at once: who has matters needing attention, who is over the US estate threshold, who is planning a move. Then the clients, most urgent first.

The client dossier

What is the client actually worth?

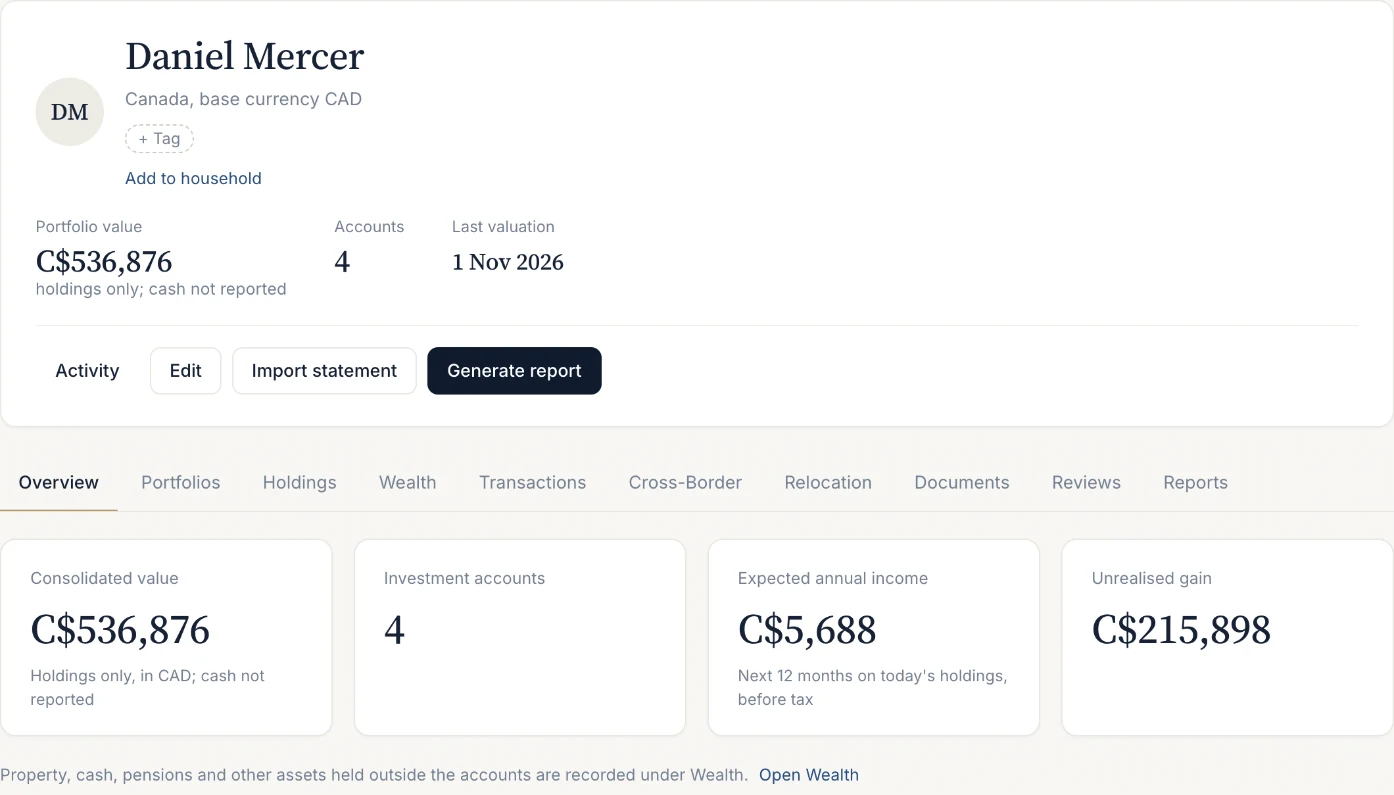
Four accounts valued in the client’s base currency, with the income expected over the next twelve months and the gain not yet realised. Cash that isn’t reported is said, not assumed.

Currency, looked through

Which currency is the money really in?

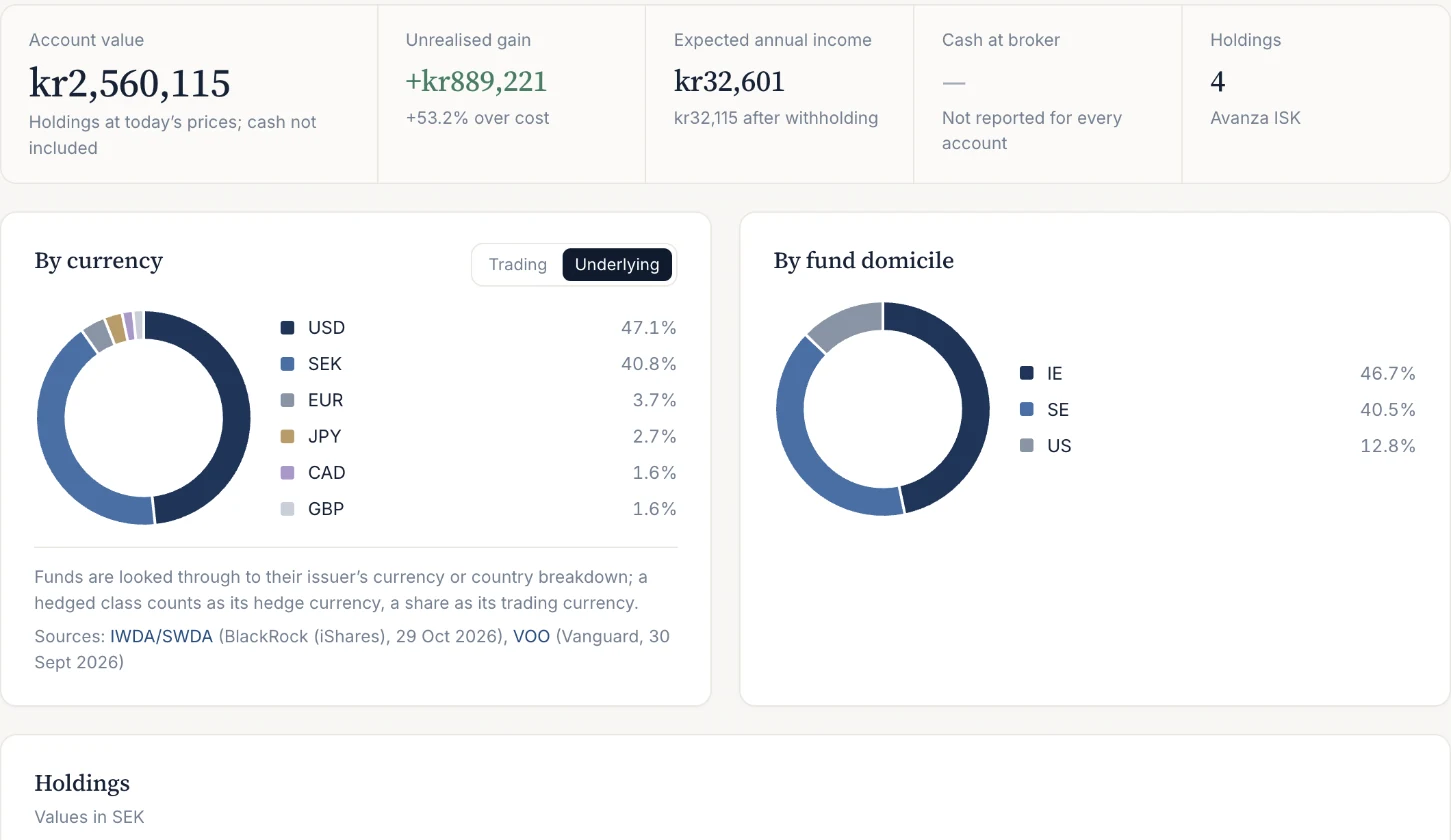
A Swedish client’s account, valued in kronor. Looking through the funds to their issuer’s breakdown, each source named and dated, 47.1% is in US dollars and only 40.8% in kronor.

Performance

How has it really done?

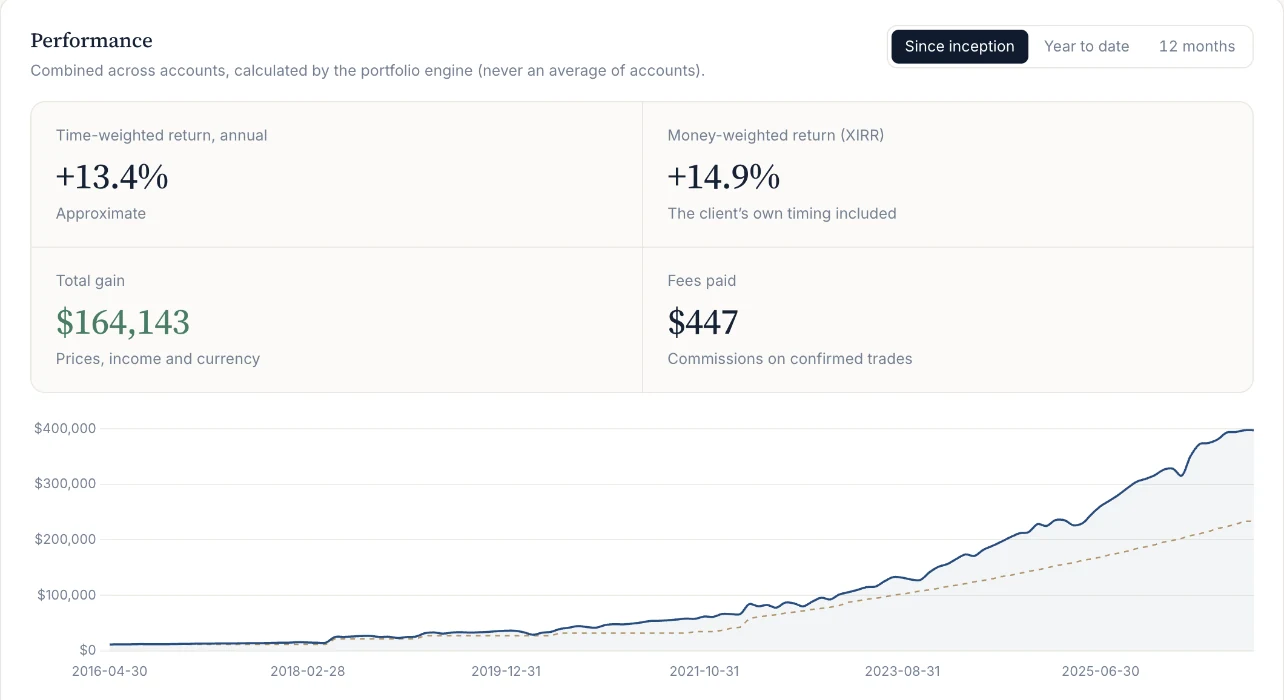
Time- and money-weighted returns combined across accounts, never an average of them, against a US-listed ETF benchmark with the withholding drag stated.

Cross-border brief

What could cost my client money?

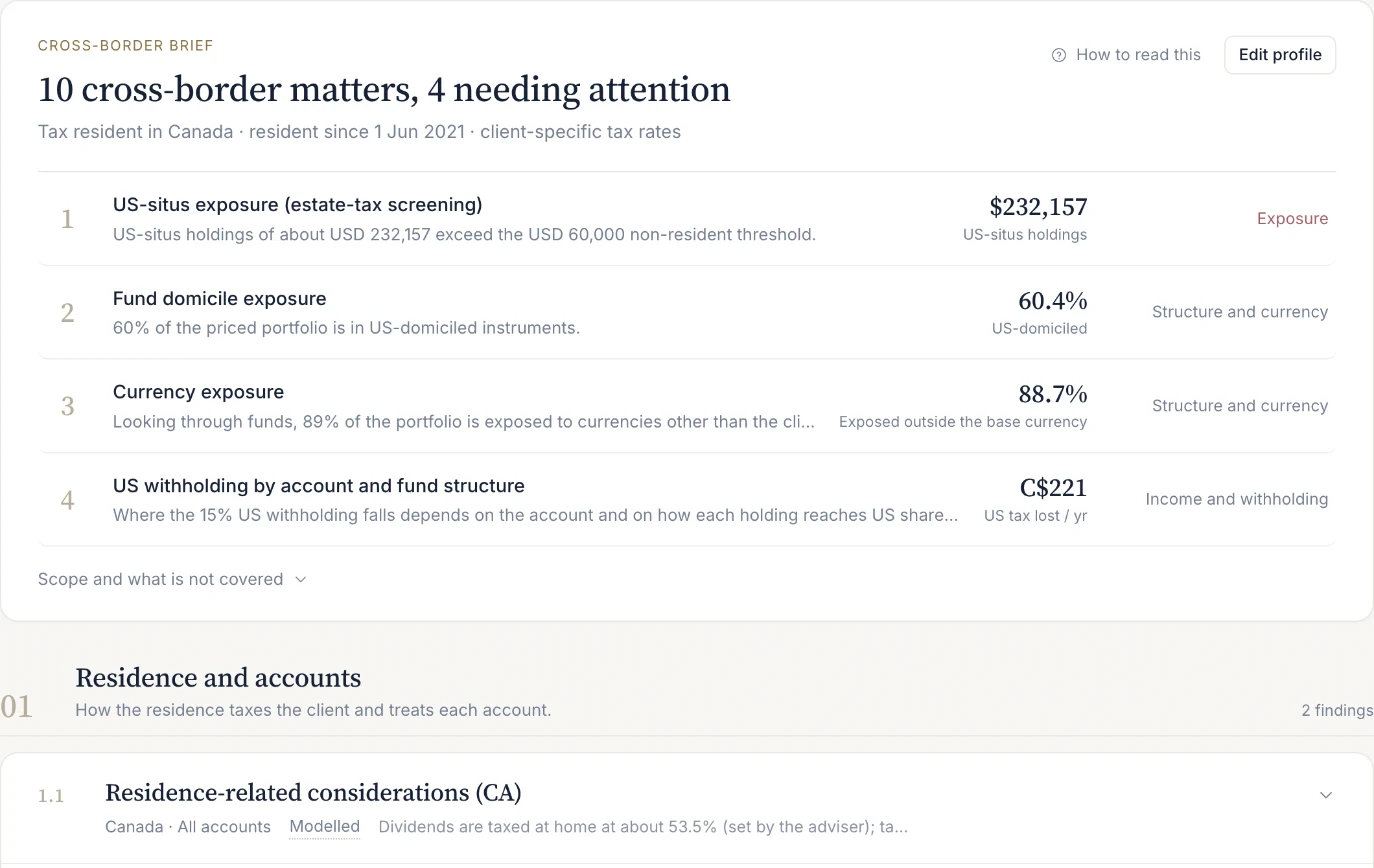
Ten matters for a Canadian resident, the four that need attention first: US-situs holdings over the USD 60,000 estate threshold, 60% in US-domiciled funds, 89% outside the base currency and C$221 a year of US tax lost by account.

European withholding

What can be claimed back?

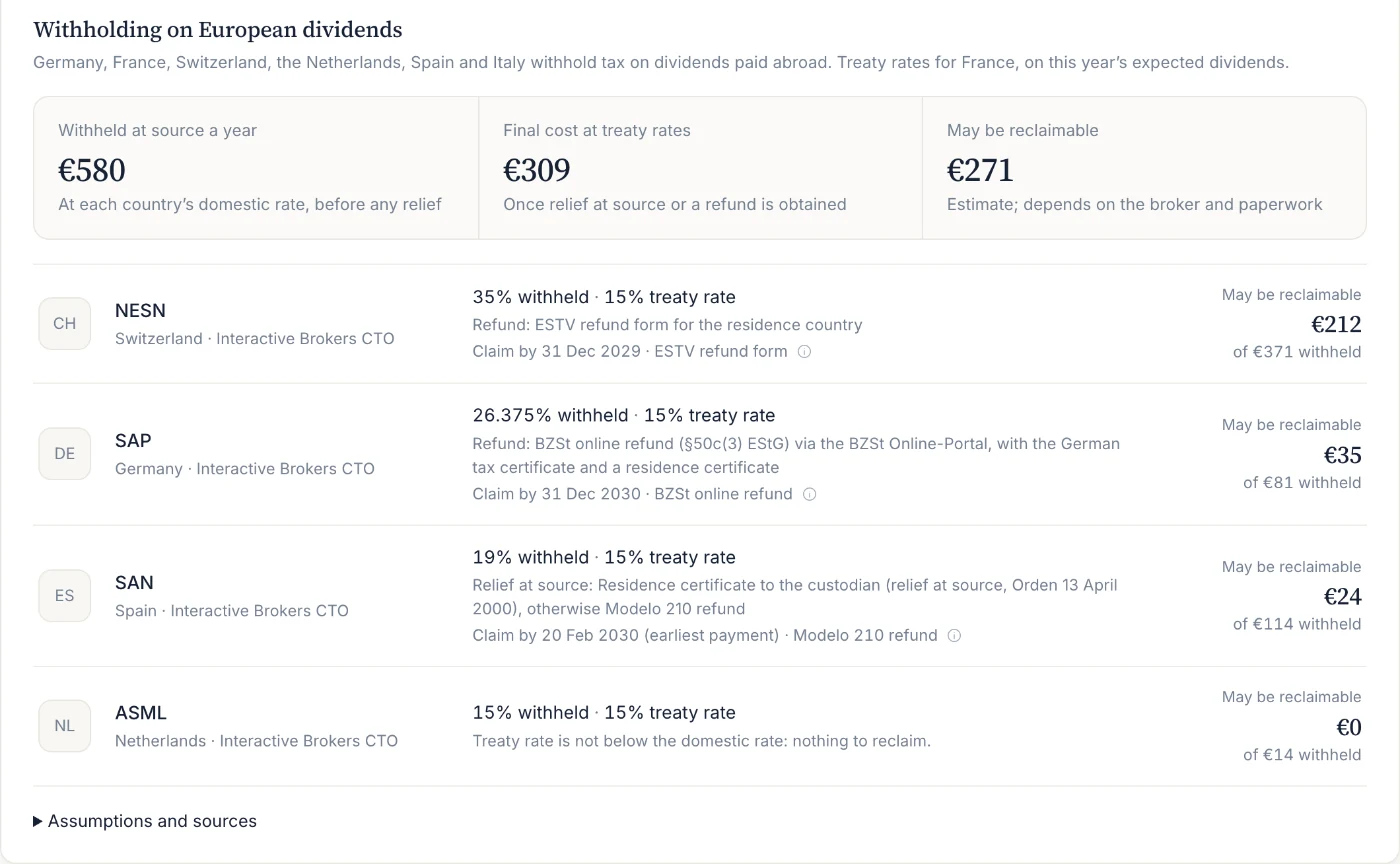
Each holding’s withholding at the source country’s rate against the treaty rate, with the route and the last day to claim. Here €271 a year may be reclaimable.

Scenarios

Should we switch this fund?

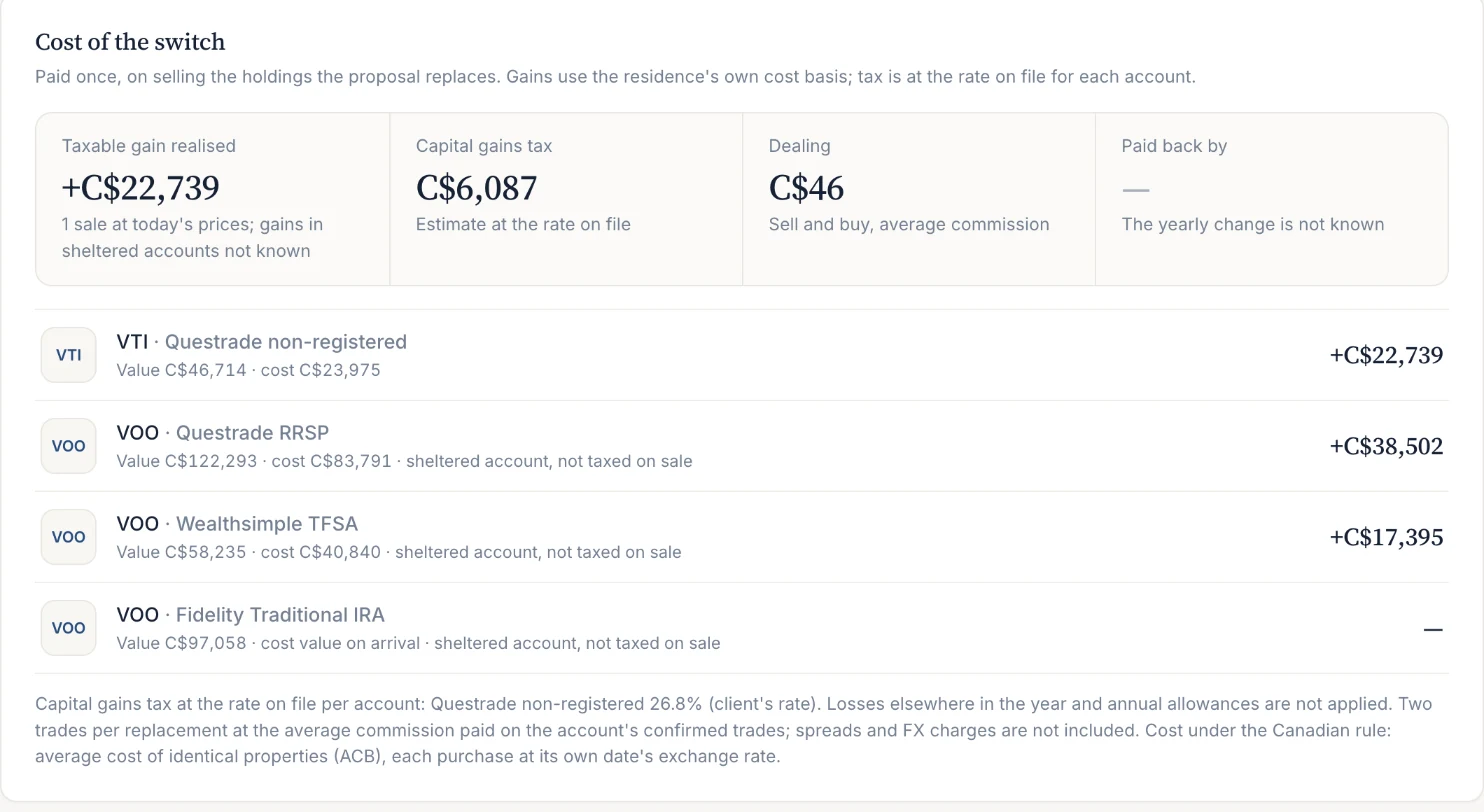
Replacing US funds with Irish ones starts with the bill: C$6,087 of tax on the one taxable sale and C$46 of dealing. The RRSP, TFSA and IRA sell without tax, and each is shown apart.

Planned move

What changes if they move?

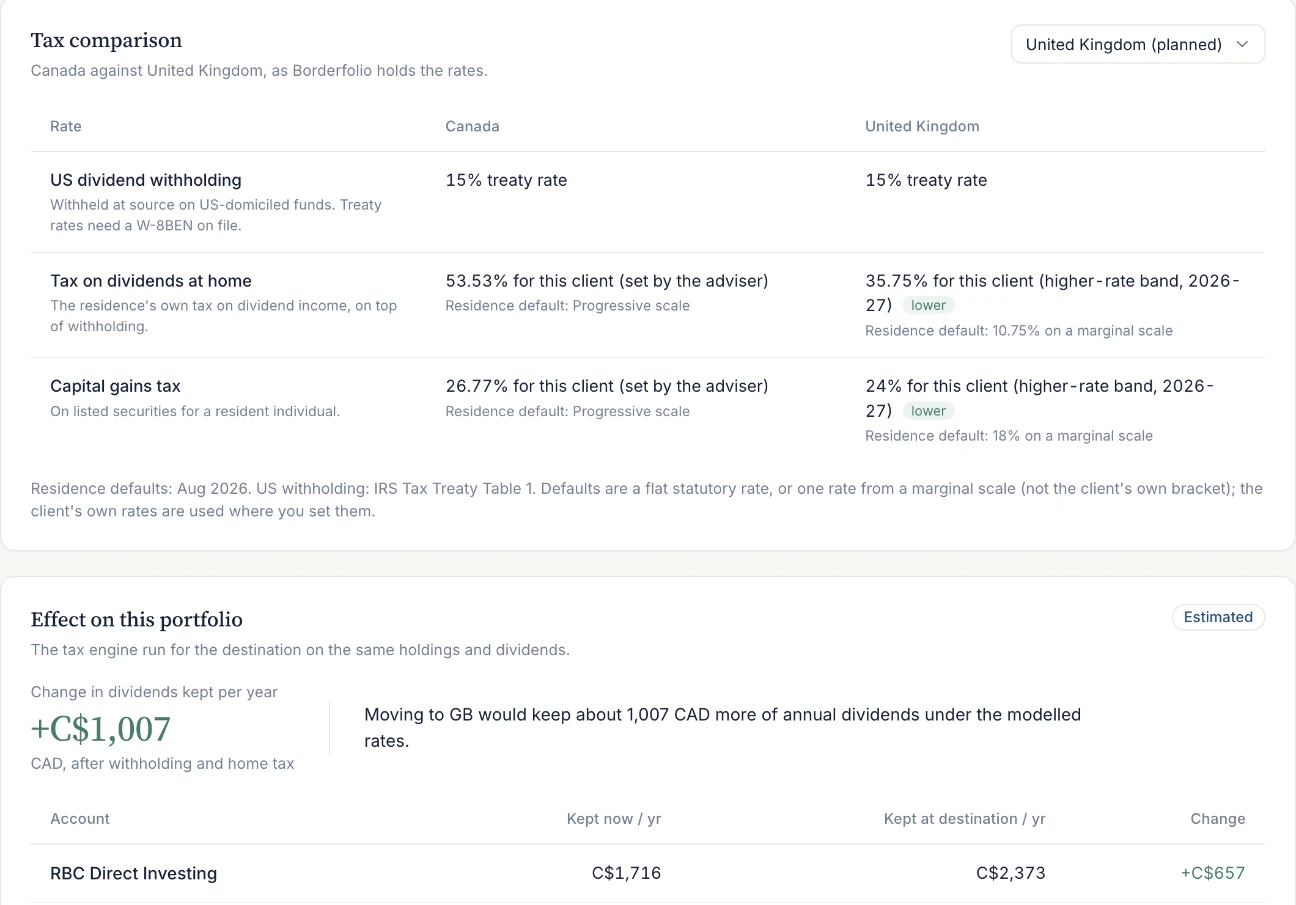
Canada at the client’s 53.53% against the UK higher rate of 35.75%, both set by the adviser: the same holdings keep about C$1,007 more in dividends a year.

Due across the firm

What is due before year end?

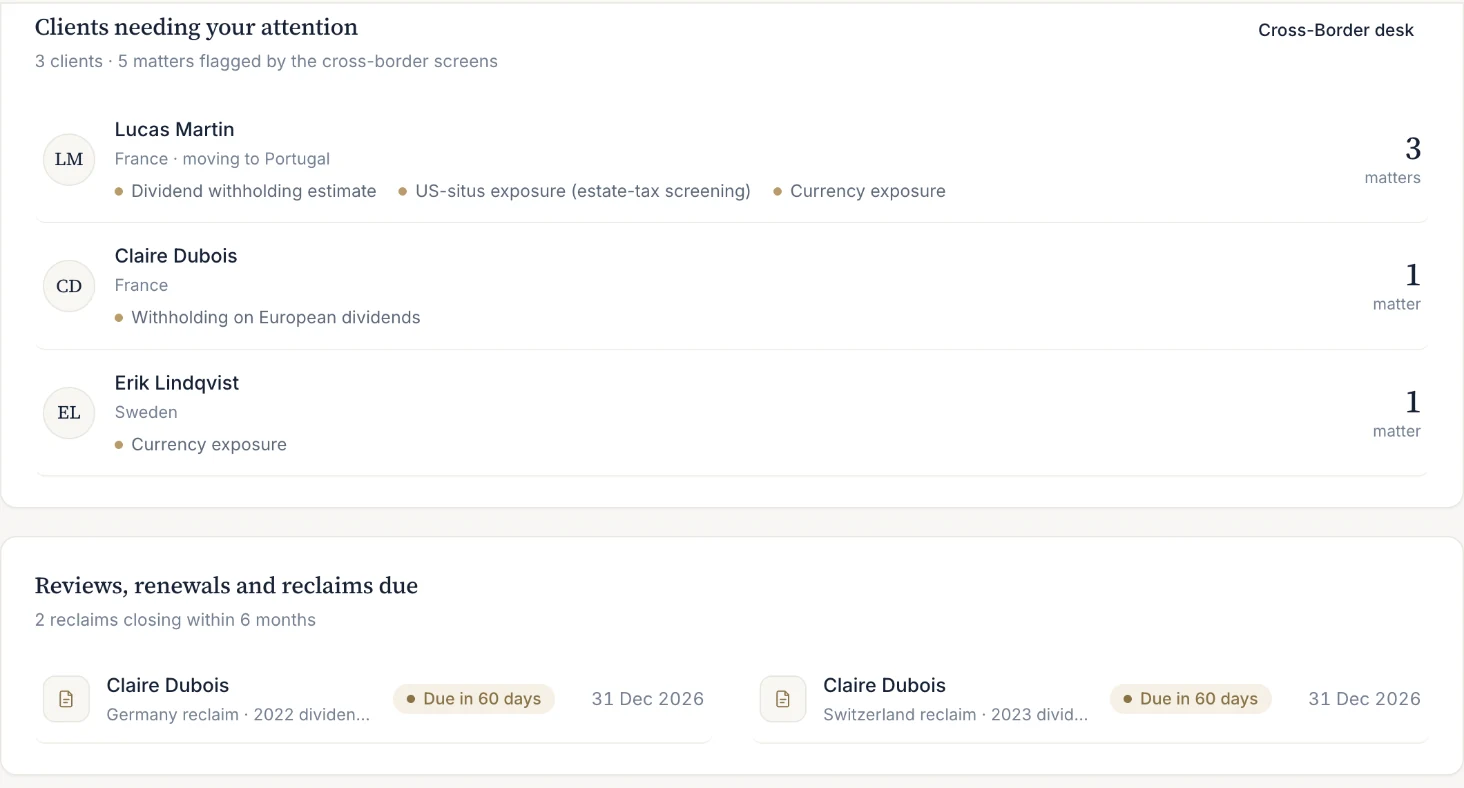
The clients needing attention and the withholding reclaims closing within six months, from every client’s checks on one page.

Try it on a sample firm

Cross-Border desk: every client screened, matters needing attention, the US estate threshold, planned moves, and clients ranked most urgent first
Client dossier: consolidated value in the client's base currency, accounts, expected income and unrealised gain
Holdings of a Swedish client in SEK: value, gain and income, allocation by underlying currency looking through funds, and by fund domicile
Performance across accounts: time- and money-weighted returns, total gain, fees paid and value over time
Cross-border brief: the client's matters ranked, with each figure and its chapter
Withholding on European dividends: withheld, treaty cost and what may be reclaimable, per holding with the route and the last day to claim
Scenario: the cost of switching — taxable gain, capital gains tax, dealing and payback, per holding with sheltered accounts shown apart
Relocation: Canada against the United Kingdom at the client's own rates, and the change in dividends kept on the same holdings
Overview: clients needing attention and the withholding reclaims closing within six months
Screens from the read-only demo workspace: fictional clients, real prices and exchange rates.Two-factor sign-in, organisation isolation and an audit trail are part of the workspace — see Security.

Who it is for

The same path, shaped by the review you are asked for.

Statements in, findings with their sources, a review under your firm’s name: what changes is the question the client brings.

Cross-border advisers

A US citizen in London, a client who has just arrived, or one about to leave the UK.

  • For US persons: each holding’s cost and gain in GBP and in USD, Irish funds screened as possible PFICs, FBAR and Form 8938, and an ISA flagged as not tax-free in the US
  • Leaving the UK: temporary non-residence with the gain held in general accounts, and the inheritance-tax tail for long-term residents
  • New arrivals: the 4-year foreign income and gains (FIG) window, for you to confirm the ten years abroad before it

Advice-only and DIY portfolio reviewers

A fixed-fee review of a DIY ETF portfolio across an ISA, a SIPP and a general account.

  • Statements through a secure upload link; InvestEngine and Vanguard Investor exports read directly, Hargreaves Lansdown, AJ Bell and Interactive Investor statements extracted and checked before anything is confirmed
  • Each offshore fund against HMRC’s reporting-fund list, and excess reportable income from the issuers’ reports for 82 share classes
  • Section 104 cost with same-day and 30-day matching, from the confirmed ledger; fees as money over 1, 5 and 10 years

Investment-led boutique firms

A prospect’s existing portfolio, reviewed before any assets move.

  • An objective second opinion: a review can say the portfolio is in order
  • Dividends and gains at the client’s 2026-27 band, basic, higher or additional, set by you and never inferred
  • The year’s ex-post costs and charges statement (COBS 16A) with each line’s provenance, and ongoing-service review records for Consumer Duty

Wrappers are set per account: Stocks & Shares ISA (Lifetime ISA included), SIPP or general account, each at its own treatment. How tax wrappers work.

The sample report

What you put in front of the client.

Each review goes out under your firm's name, with your commentary set apart from Borderfolio's analysis, and never changes after you send it. Every figure states its source and the assumption it rests on; what is not calculated is labelled, not estimated.

  1. Executive portfolio summary1
  2. Portfolio allocation2
  3. Holdings overview3
  4. Performance summary4
  5. Dividends and fees5
  6. Currency and fund-domicile exposure6
  7. Cross-border considerations7
  8. Adviser notes8
  9. Sources, assumptions and limitations9

Illustrative pages; figures are examples.

Pages of a generated report for a fictional client resident in the United Kingdom, at real prices, are in the United Kingdom brochure (PDF). Each other country’s site has its own brochure: choose a country.

Security and trust

Your clients’ statements, kept private and under your control.

Advisers upload statements that are not their own, and the workspace is built around that. This describes the product as built, not a certification.

Read the full description
Workspace isolation
Every request is authorised against the adviser’s organisation; an identifier that belongs to another firm reads as not found.
Access controls
Owners manage settings, members and deletions; advisers work with clients, imports and reports. Enforced on the server.
Two-factor authentication
One-time codes with single-use recovery codes. A firm can require it for every member.
Document handling
Files are checked against their declared type. Original statements are purged after seven days; there are no public document links.
Audit history
Imports, confirmations, downloads, reports and membership changes are recorded with the acting adviser.

Plans and pricing

One price per firm, stated in full.

Every plan includes the whole workspace: statement import and review, consolidation, cross-border findings, relocation planning, scenarios and PDF reviews. Plans differ in how many advisers, clients and imports they carry, and in how reports are branded. Firms beyond these limits can ask for a quote.

Founding programme, first 25 firms

Founding Adviser

$99a month

30-day trial without a card. Held for your first 12 monthly payments, or your first year at $999, then the Advisor rate.

Annual billing
$999 a year
Advisers
1
Active clients
50
Extra clients
+25 for $29 a month
Statement imports a month
30
Report branding
Firm name
Shared workspace
Not included

For one adviser

Advisor

$149a month

The full workspace for an independent adviser. Annual billing costs ten monthly payments.

Annual billing
$1,490 a year
Advisers
1
Active clients
50
Extra clients
+25 for $29 a month
Statement imports a month
30
Report branding
Firm name
Shared workspace
Not included

For a small team

Practice

$299a month

Shared clients and branded reports for up to three advisers. Annual billing costs ten monthly payments.

Annual billing
$2,990 a year
Advisers
3
Active clients
150
Extra clients
+25 for $29 a month
Statement imports a month
100
Report branding
Firm name, logo and contact block
Shared workspace
Owner and adviser roles, shared clients

For a firm with its own platform

White Label

$499a month

The workspace on your own domain under your brand, without Borderfolio attribution.

Annual billing
$4,999 a year
Advisers
25
Active clients
500
Extra clients
On request
Statement imports a month
1,000
Report branding
Your brand only, on your own domain
Shared workspace
Owner and adviser roles, shared clients

More clients than your plan carries

Need more clients? Add 25 for $29 a month ($290 a year on annual billing), on the Founding Adviser, Advisor and Practice plans. How packs work.

Start with a plan

Larger firms and specific terms

More than 25 advisers or 500 active clients, more extra clients than the packs above, annual invoicing, or contract and data-processing terms of your own: tell us what your firm needs and we reply personally with a quote within two working days.

Request a quote

The 30-day trial, without a card, comes with the Founding Adviser plan only. Advisor, Practice and White Label start with the first payment: you create the workspace, then pay for the plan in it. Archived clients do not count towards the active-client limit; extra-client packs add 25 places each for $29 a month. Prices are in US dollars and exclude VAT where it applies. Billing is per firm through Freemius, the merchant of record; cancel at any time, and the first payment is refundable within 14 days (billing and refund policy).

Questions UK advisers ask

Plain answers.

How are ISAs, SIPPs and general accounts treated?

Each account is set as an ISA (a Lifetime ISA included), a SIPP or a general account. Inside an ISA or a SIPP there is no UK tax on income or gains. US dividends in an ISA bear the 15% treaty rate with a W-8BEN, a final cost with no UK tax to set it against; a SIPP its provider has documented receives dividends from US-domiciled funds free of US withholding under the UK–US treaty, a relief an Irish fund loses inside the fund. General accounts are taxed at the 2026-27 band you set: basic 10.75% on dividends and 18% on gains, higher 35.75% and 24%, additional 39.35% and 24%. Without one, the basic rate is used and labelled as the residence default.

Does it check reporting-fund status and excess reportable income?

Each offshore fund is matched by ISIN to HMRC’s list of reporting funds, loaded monthly, and the list’s date is shown; many US-listed ETFs are reporting funds, so the status is checked, never assumed. Excess reportable income comes from the issuers’ own reports: 549 reporting periods for 82 share classes from Vanguard, iShares, Invesco, SPDR, Xtrackers and HSBC, from 2019. The units held in general accounts at each period end are multiplied by the reported figure, placed in the tax year of the fund distribution date and added to the Section 104 cost. A fund held without a report on file is named, never estimated.

How is the cost of a holding worked out?

From the confirmed transactions, each trade at its own date’s exchange rate. A sale is matched first with purchases on the same day, then with purchases in the following 30 days, and only then with the Section 104 holding (TCGA 1992 s.105 and s.106A). Purchases inside an ISA or a pension are outside that ledger, so selling in a general account and buying back in an ISA realises the gain. Excess reportable income raises the cost of the holding. A holding missing from the ledger, or held in a different quantity, has no known cost and is named, never guessed.

Can it read InvestEngine, Vanguard, Hargreaves Lansdown and AJ Bell statements?

InvestEngine and Vanguard Investor exports are read directly, as are Trading 212, Freetrade and Interactive Brokers Flex exports, and an IBKR account can also be synced daily. Hargreaves Lansdown, AJ Bell and Interactive Investor statements go through the extraction model. Either way every position and transaction is shown for review, and nothing reaches the client’s holdings until you confirm it. A client can send statements through a secure upload link without opening an account.

What does it show for a client leaving the UK, or a US person living here?

The UK has no exit charge, so for a planned move the review shows the two rules that follow the client. Temporary non-residence: a client who was UK resident in at least four of the seven tax years before leaving and returns within five years is taxed, in the year of return, on gains made abroad on assets held at departure; the net unrealised gain in general accounts is shown. Inheritance tax: after 10 of the last 20 years a client is a long-term resident, and worldwide assets stay within UK inheritance tax for 3 to 10 tax years after leaving. For a US person: each holding’s cost and gain in GBP and in USD, Irish and other non-US funds screened as possible PFICs, FBAR and Form 8938 thresholds, US estate exposure, and an ISA flagged as not tax-free in the US. Split years, the inheritance tax itself, US returns and the PFIC tax are not computed.

How do the trial and extra-client packs work?

The Founding Adviser plan comes with a 30-day trial and no card: open a workspace yourself, and pay 99 USD a month when the trial ends. That price is open to the first 25 firms and held for their first 12 monthly payments, or for the first year on annual billing at 999 USD. Advisor, Practice and White Label have no trial and start with the first payment. Or tell us about your firm using the form below and we reply personally within two working days to help set it up.

Add active clients in packs of 25 for $29 a month each, on the Founding Adviser, Advisor and Practice plans. Add them from Settings, Plan and usage, once your plan is active: each pack is its own small subscription at exactly $29 a month ($290 a year on annual billing), so a second pack costs the same as the first. Cancel a pack at any time, and cancelling your plan stops its packs too; clients above the new limit stay readable, but no further client can be added or restored until you are within it. Packs stop counting if the subscription lapses. Households do not use extra places: each person is one client, and trusts, SMSFs and joint accounts are accounts of a member.

Review a portfolio together

A more considered way to review client portfolios.

Bring one client or prospect and we will work through the review with you: importing their statements, reading the findings and preparing the report. We set up a small number of firms personally.

Steffan Kharmaaiarvi, founder of Borderfolio

You work with the founder. Steffan Kharmaaiarvi sets up each early firm personally and works through the first client review with you. About · LinkedIn

Prefer to start on your own? Open a workspace with the Founding Adviser 30-day trial, no card needed; plans and prices are listed above.

Clients you advise
We read every request personally.

Bring a clearer perspective to every client portfolio.

Discover a more thoughtful approach to portfolio reviews and international investment analysis.