Canadian departure taxESTIMATED · ATTENTION
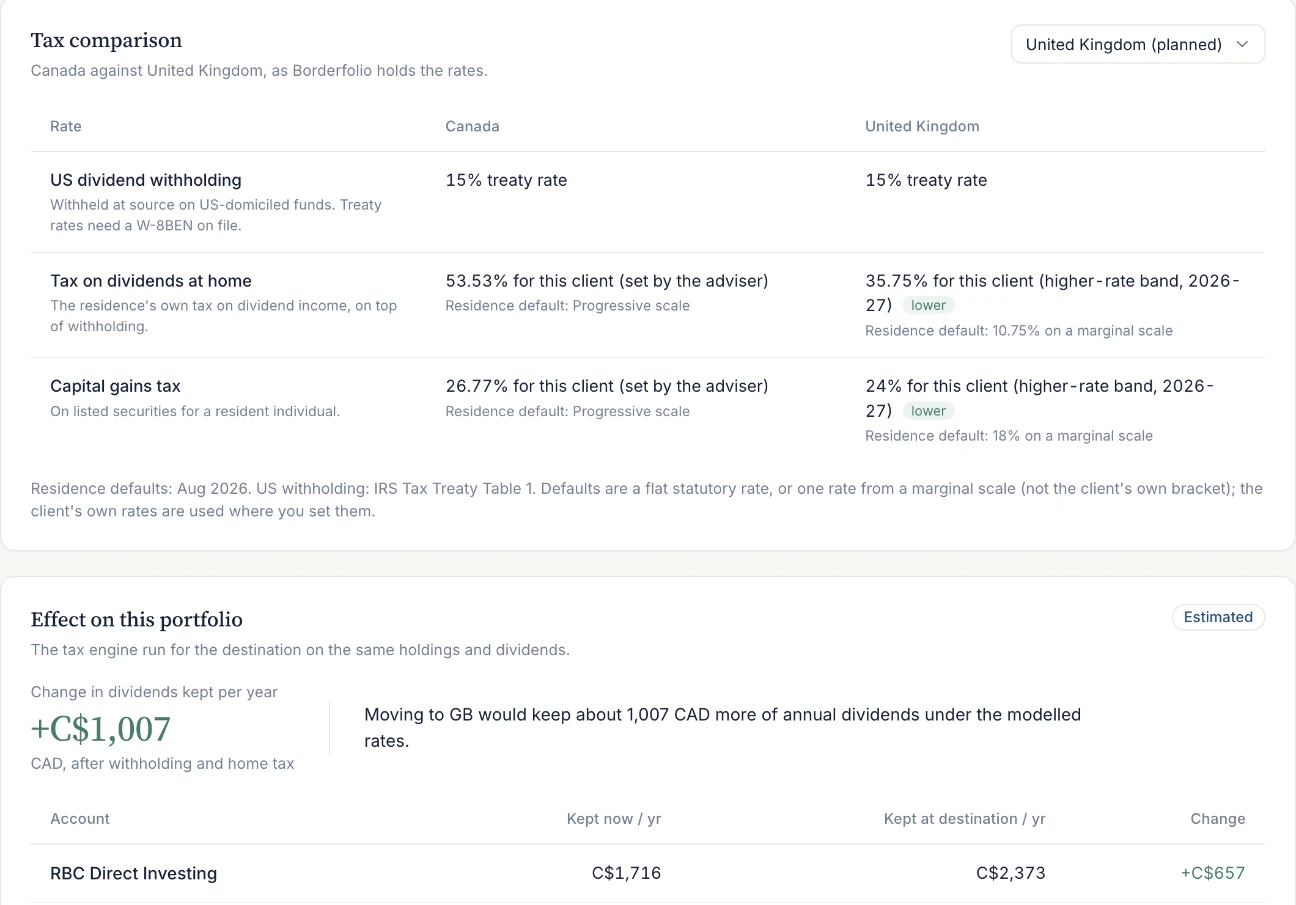
Leaving for the United Kingdom on 30 June 2027: a deemed gain of about CAD 96,480 on the non-registered account, of which CAD 48,240 is taxable. T1243 and T1161 are due; T1244 can defer the tax.
- Assumes
- Canadian average cost, each purchase at its own date’s rate, return of capital applied; RRSP and TFSA left out; today’s prices
- Source
- Confirmed transactions; Income Tax Act s.128.1; CRA, leaving Canada